The US Federal Reserve’s latest rate hike may have been largely anticipated by markets, but its implications for India could be more significant. With the India-US 10-year bond yield differential near multi-decade lows, the Fed’s tighter policy stance is reducing the Reserve Bank of India’s room to pursue aggressive easing.
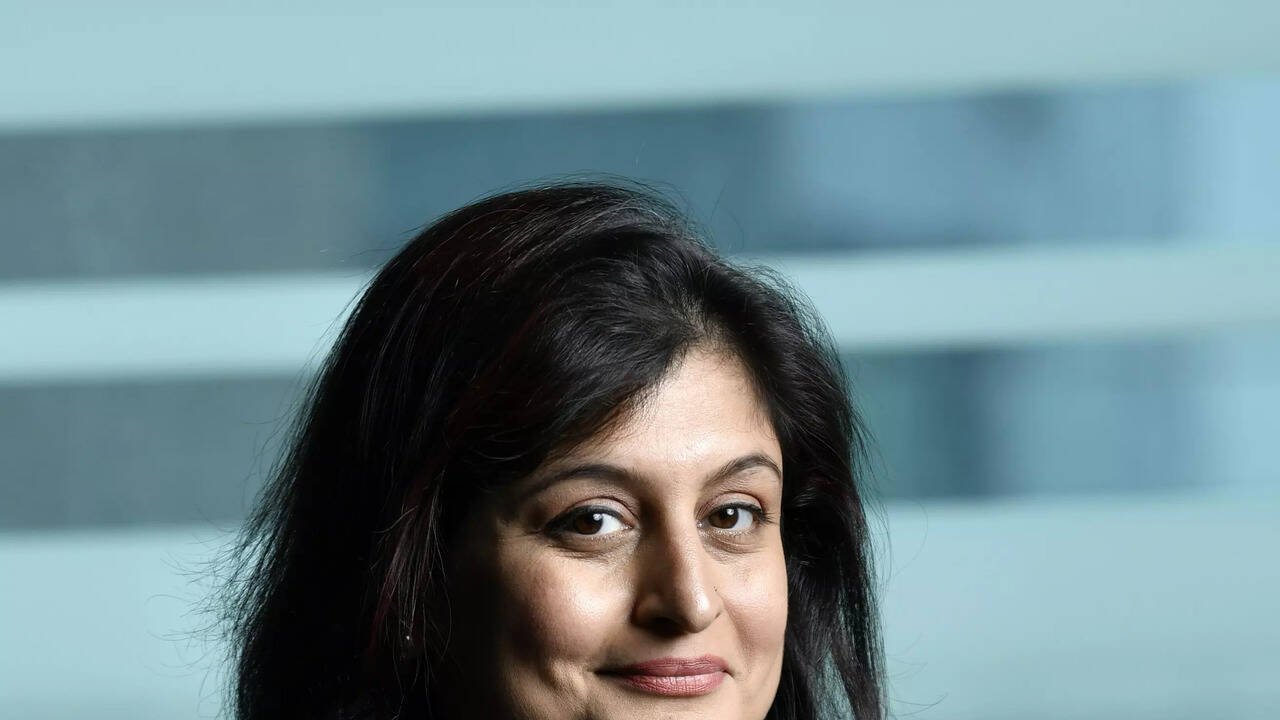
Garima Kapoor, Deputy Head of Research & Economist at Elara Securities, expects India could see 25–50 bps of rate hikes in 2026, with the October and December meetings likely to be key. She says rising domestic inflation, elevated crude prices, pressure on the rupee and a narrowing interest-rate differential with the US are increasingly constraining the RBI’s policy flexibility.
For Indian equities, however, the Fed hike itself may be less important than what happens next to US Treasury yields and the dollar. Sustained higher US yields and a stronger dollar could keep FPI flows under pressure, tighten global financial conditions and raise the hurdle rate for emerging-market equities.
At the same time, Kapoor believes the shift in global rates has made US fixed income a genuine alternative for global investors after years of ultra-low yields. This could keep foreign investors cautious on emerging markets such as India until US yields peak or EM risk premia become more attractive.
So, as investors navigate a potentially tighter domestic rate cycle, weak FPI flows and elevated global yields, the key question is: how much room does India really have to remain insulated from the Fed?
In this edition of ETMarkets Smart Talk, Garima Kapoor decodes what the latest Fed move means for the RBI, Indian equities, the rupee, FPI flows and the broader investment landscape. Edited Excerpts -
Q) The Fed has raised rates by 25 bps, but markets were largely expecting it. What does it mean for Indian markets?
A) The Fed’s 25 bps hike (to 3.75–4.00%) on 16 September 2026 was fully anticipated and unanimous under Chair Kevin Warsh. Markets priced it at 90% probability. Because the move was priced in, the immediate reaction was muted.
Indian equities did not respond too severely. For Indian markets, the Fed’s rate hike means the likely beginning of the India rate hike cycle. With the India-US 10-year bond yield spread at ~ 200 bps, which is near multi-decade lows and roughly half of its long-term historical average, the degrees of freedom for the RBI are getting limited.
A beginning of a rate hike cycle starting in October 2026 may impact the rate-sensitive sectors. Banking stocks may find some support from better yields/margins, especially after record FCNR(B) deposits.
However, with continuing geopolitical tensions, overall volatility is expected to stay elevated. Domestic institutional and retail flows will be critical to support the market as FPI flows are expected to remain weak.
Q) For Indian equities, should investors be more worried about the Fed itself or the resulting move in US bond yields and the dollar?
A) The US bond yields and the dollar are the more important channels. The Fed decision is the trigger, but transmission to India occurs mainly through:
Higher US Treasury yields (short-end yields rose meaningfully; 10-year yields moved around 5%), which tighten global financial conditions and raise the opportunity cost of holding emerging-market equities.
A firmer dollar, which pressures the INR, raises imported inflation and encourages capital to flow toward USD assets, especially at a time when US markets are offering attractive returns.
EM equities, including Indian equities, respond more to the level and persistence of US yields and the dollar than to the precise wording of the FOMC statement. Sustained high US yields + strong dollar = continued FPI selling pressure and higher cost of capital. A quick peak-and-pivot by the Fed would ease those pressures; a higher-for-longer path would keep them in place.
Q) If the Fed delivers another rate hike this year, what could that mean for global risk assets, emerging markets and capital flows?
A) Markets already assign a solid probability to another hike of 25 bps in December 2026. This may further push short-end US yields higher and support the dollar partially, raising the relative attractiveness of US fixed income versus risk assets.
This could tighten global liquidity and increase funding costs, thereby intensifying pressure on emerging-market capital flows (especially equities and local-currency debt).
For India, this would likely extend FPI outflows and constrain equity valuation expansion until US yields stabilise or domestic earnings growth proves strong enough to offset the higher global hurdle rate.
Q) What does the Fed’s latest move mean for the RBI? Does India have enough room to pursue an independent monetary policy?
A) The Fed’s shift raises the bar for any further RBI easing and increases the odds of domestic tightening. India’s repo rate currently stands at 5.25%.
With domestic inflation rising, crude elevated, the INR under pressure and the interest-rate differential with the US narrowing, we expect the RBI to deliver 25–50 bps of hikes in 2026 (October and December meetings), keeping the overall cycle at 50 bps for now.
Liquidity normalisation measures (OMO sales, VRRRs, forex swaps) are already under way. Once the Fed hikes, the room for independence gets constrained for the RBI amid multi-decade low interest rate differentials and elevated crude oil prices.
Q) Does a higher-rate environment make US fixed income more compelling for global investors compared with the previous decade of ultra-low yields?
A) Yes. After more than a decade of near-zero or negative real yields across much of the developed world, US Treasuries and other high-quality USD fixed-income assets now offer meaningfully positive nominal yields in the 4–5%+ range on intermediate maturities.
This restores a genuine low-risk income alternative that was largely missing in the 2010s and early 2020s. Higher US yields raise the hurdle rate for equities and EM debt.
This structural change supports the higher-for-longer narrative for US rates and helps explain continued FPI caution toward emerging markets like India until either US yields peak or EM risk premia become large enough to compensate.